Florida Home Insurance Secrets: Forced Placement, CLUE Reports & Credit Scores
Force-placed insurance, CLUE reports, and insurance scores are three hidden mechanisms that can quietly double — or eliminate — a South Florida homeowner’s coverage options. Understanding all three puts you back in control before your next renewal or home purchase.
Updated September 2026
Key Takeaways
- Force-placed insurance is lender-ordered coverage when your policy lapses — it protects the bank, not you, and costs significantly more.
- Your CLUE report records home insurance claims and follows the property, not just the owner — prior-owner claims can affect a new buyer.
- Insurers use an insurance score (not your FICO score) that includes soft credit data — improving it can lower your premium.
- Florida has seen multiple carrier insolvencies since 2021; knowing how to spot a financially shaky carrier matters.
- A new qualifying roof can improve your wind-mitigation report and make your home insurable again after a non-renewal.
The Problem
Why Florida Homeowners Get Blindsided by Insurance
Three invisible factors that can make coverage disappear or become unaffordable.
Florida’s home insurance market is one of the most volatile in the country. Since 2021, more than a dozen carriers have been declared insolvent or have voluntarily left the state. What’s left is a smaller pool of carriers — many of which are tightening eligibility rules around roof age, claim history, and credit-based insurance scores. Most homeowners don’t find out they have a problem until they get a non-renewal letter in the mail or a mortgage statement showing a force-placement charge.
The three mechanisms below — force placement, CLUE reporting, and insurance scoring — work quietly in the background. None of them require your consent to affect you. But each of them can be addressed once you understand how they work.
South Florida Context
Why Miami-Dade and Broward Face Extra Scrutiny
The HVHZ designation adds layers of underwriting complexity most markets never see.
Miami-Dade and Broward counties sit inside the High-Velocity Hurricane Zone (HVHZ) — the strictest residential building-code jurisdiction in the United States. Insurers know this. Underwriters who write policies in this market apply tighter rules around roof materials, roof age, and wind-mitigation credits than anywhere else in Florida. A 20-year-old flat roof in Miami-Dade that might slide by in Central Florida is a non-renewal waiting to happen here.
Citizens Property Insurance has been actively non-renewing policies on homes with roofs that have exceeded their underwriting age threshold. Private carriers often set the bar even lower — some will not write a new policy on a home with an aging roof regardless of condition. That single factor — roof age — is the most common reason Miami-Dade and Broward homeowners end up force-placed.
What You Need to Know
Force-Placed Insurance, CLUE Reports & Insurance Scores — Explained
Force-Placed Insurance (Lender-Placed Coverage)
Force-placed insurance — sometimes called lender-placed or creditor-placed insurance — is coverage your mortgage lender orders on your behalf when your homeowner’s policy lapses or is cancelled. The lender does this to protect its financial interest in the property. The policy covers the structure only, not your personal property, not your liability, and often not the full replacement cost of the home. And it is almost always more expensive than a standard market policy for equivalent coverage.
How it happens: your insurer sends a non-renewal notice. The notice goes to an old address or gets missed. Your policy lapses on the expiration date. Your lender’s escrow system detects the coverage gap, typically issues a warning, then orders a force-placed policy and charges your escrow account. By the time you notice the higher mortgage payment, the force-placed policy may already have been in place for months.
The fix is straightforward once you know: secure a replacement policy, provide proof of insurance to the lender, and request cancellation of the force-placed policy with a refund of any unearned premium. The harder part is finding coverage in a market where your non-renewal may itself be a red flag to new carriers.
CLUE Reports — How Claim History Follows a Home
CLUE stands for Comprehensive Loss Underwriting Exchange. It is a database maintained by LexisNexis that records property insurance claims at a given address — typically covering a multi-year lookback window. Every insurer you have ever had (and most of the ones you apply to) reports claims to CLUE and queries it when underwriting a new policy.
Two things surprise most homeowners about CLUE reports:
- The record follows the property, not just you. If the previous owner of your home filed two water-damage claims, those claims appear on the CLUE report for that address. A new buyer can be denied coverage — or charged higher premiums — for claims they had nothing to do with.
- Inquiry entries can appear even if no claim was paid. In some states, even a call to your insurer asking whether something is covered — without filing a formal claim — can create a CLUE entry. Florida law gives you the right to obtain one free CLUE report per year and to dispute inaccurate entries through LexisNexis.
Before you buy a home in South Florida, request the CLUE report for the property address. A pattern of water claims — roof leaks, plumbing failures, mold — tells you something about the home’s maintenance history that the seller’s disclosure may not.
Insurance Scores — The Soft Credit Pull You Did Not Know About
Your insurance score is not the same as your FICO credit score, but it is calculated from much of the same data — payment history, open accounts, length of credit history, recent inquiries. Insurers license proprietary scoring models that weight credit factors alongside claims history to predict the statistical likelihood of a future claim. A lower insurance score typically produces a higher premium, and in some cases can result in a declination.
Importantly, the insurer’s pull is a soft inquiry — it does not affect your FICO score and it does not appear on your credit report the way a mortgage application does. But the data it draws from is real credit data. Over time, paying down revolving balances, removing collection accounts, and reducing recent hard inquiries can improve your insurance score and open up carrier options that may not have been available to you previously — though the timeline varies by individual credit profile.
| Factor | What Insurers Look At | What You Can Do |
|---|---|---|
| Roof age / condition | Age, material, permit history | Replace aging roof; obtain wind-mit report |
| CLUE claim history | Claims at address, multi-year lookback | Request report; dispute errors; disclose proactively |
| Insurance score | Credit-based model, soft pull | Reduce balances; clean up collections |
| Carrier solvency | Demotech / AM Best rating | Verify rating before binding; ask agent for alternatives |
| Wind-mitigation credits | Roof shape, straps, opening protection | Schedule a wind-mit inspection after roof replacement |
Carrier Landscape
Admitted Carriers vs. Surplus Lines — What the Difference Costs You
Not all Florida home insurance policies carry the same backstop if the carrier fails.
| Feature | Admitted Carrier | Surplus Lines Carrier |
|---|---|---|
| Florida Insurance Guaranty Association (FIGA) backstop | Yes — up to statutory limits | No — you bear the insolvency risk |
| Rate filing required | Yes — OIR approval | No — rates set by market |
| Availability in hard market | Limited — carriers exiting | Broader — will write what admitted carriers won’t |
| Typical premium | Often lower when available | Often higher; varies widely |
| Agent access | Standard appointments | Requires surplus lines broker |
Florida has seen admitted carriers become insolvent with little warning. When that happens, FIGA steps in to pay admitted carrier claims up to its statutory limits — but only for admitted policies. Surplus lines policies have no such safety net. That does not make surplus lines bad; in a hard market they may be the only option. But you should know which type you are buying.
Agent appointments also limit what your agent can quote. Not every agent has contracts with every carrier. If your agent returns three quotes and they all look similar, it may be worth asking an independent broker who specializes in the South Florida market to run a broader search.
Why This Matters for Your Roof
The Roof Is the Single Biggest Insurance Underwriting Variable You Can Control
A qualifying replacement roof — properly permitted and inspected — changes what carriers will write and what they charge.
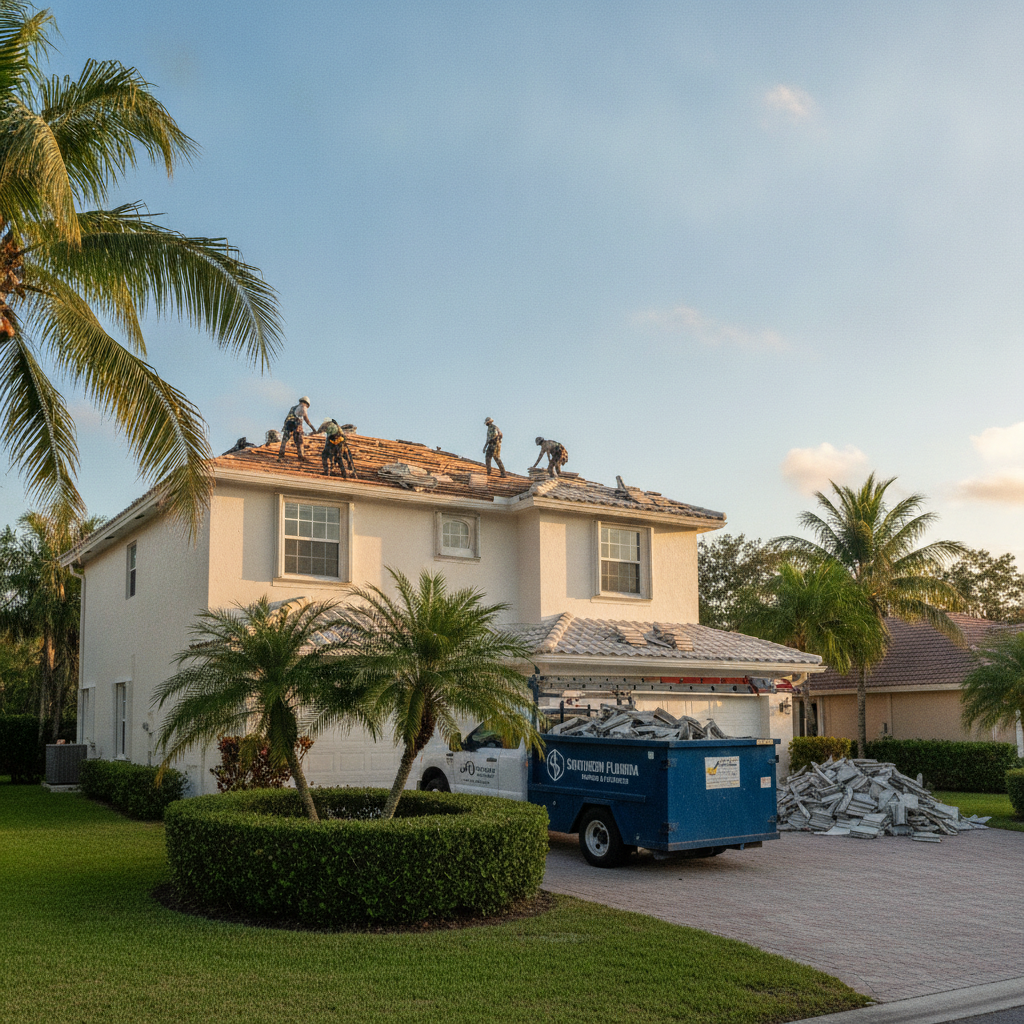
In South Florida, the roof age and material are the first two things most underwriters look at. An old three-tab shingle roof or a deteriorating flat membrane is a non-renewal trigger. A new architectural shingle roof with a qualifying peel-and-stick underlayment, or a standing-seam metal roof, is a different conversation entirely. Carriers will write policies on it. Wind-mitigation credits become available. And in some cases, the annual premium drops significantly after a new roof and wind-mit report are submitted.
When the scope of a roof replacement also involves structural work — hurricane strap upgrades, header corrections, or deck repairs — those items need to be handled under the right license authority. Bigfoot performs hurricane strap upgrades and structural modifications under a Certified General Contractor license (CGC1531370), which means structural scope does not require a separate contractor or a second permit. That kind of coherent, single-contractor accountability is particularly valuable in Miami-Dade, where inspectors scrutinize every permit and documentation gap can delay your final inspection.
“The roof is the underwriting trigger most homeowners don’t control until it’s too late. A new qualifying roof — pulled under permit, inspected, and documented — is the single most concrete thing you can do to keep your policy intact in this market.”
President, Bigfoot Windows & Roofing
Roof Options That Help with Insurability
Which Roof Systems Support Better Wind-Mitigation Outcomes
Not all replacement roofs are equal in the eyes of a wind-mitigation inspector.
A wind-mitigation inspection grades your home on several factors: roof shape (hip vs. gable), roof deck attachment, roof-to-wall connection (hurricane straps or clips vs. toe-nails), and secondary water resistance (qualifying underlayment). The score drives meaningful insurance credits — but only if the roof system is installed correctly, permitted, and documented with the inspection forms the insurer requires.
Roof systems Bigfoot installs that support wind-mitigation credits in Miami-Dade and Broward include:
- Architectural shingle with peel-and-stick underlayment: Under current Florida Building Code standards applicable in Miami-Dade and Broward, a full-deck peel-and-stick application can qualify as a secondary water barrier — the credit category that often produces the largest premium reduction. Confirm the specific edition requirements with your licensed roofing contractor. Installed cost in South Florida typically runs $750–$850 per square (per Bigfoot Windows & Roofing, 2026).
- Standing-seam metal (Englert): A continuous-panel standing-seam system with Englert-stamped clips and no horizontal seams is one of the strongest wind-load systems available in the HVHZ. Installed cost typically runs $1,050–$1,300 per square (per Bigfoot Windows & Roofing, 2026).
- Concrete or clay tile with foam adhesive: Westlake poly-set foam adhesive tile attachment is rated to 180 mph in South Florida conditions (per Bigfoot Windows & Roofing warranty documentation). Tile installed cost typically runs $1,000–$1,350 per square depending on profile and complexity.
After any qualifying replacement, Bigfoot recommends scheduling a wind-mitigation inspection through a licensed inspector. The resulting OIR-B1-1802 form is what you submit to your insurer to unlock the credits. If hurricane straps need upgrading as part of the roof replacement scope — a common finding on pre-2002 homes in Miami-Dade — that structural work can be addressed under one permit through Bigfoot’s roofing and general contractor scope.
Homeowners managing the cost of a full replacement can also explore financing options including PACE, which is paid through the property tax bill and does not require a traditional bank approval.
What Happens Next
From Roof Replacement to Wind-Mitigation Credit — the Process
- Estimate and scope review: Bigfoot inspects the roof, identifies any structural issues (straps, deck, headers), and provides a written scope and qualified price range. Structural modifications, when needed, are handled in-house under CGC1531370 — no separate general contractor required.
- Permit pulled: A permit is pulled through the county building department. Miami-Dade permit review typically takes two to six weeks for standard residential replacements (per Bigfoot Windows & Roofing).
- Installation and county inspection: The roofing system is installed and inspected by the county. This generates the permit record that a wind-mitigation inspector and your insurer rely on.
- Wind-mitigation inspection: After the final inspection passes, a licensed wind-mitigation inspector completes the OIR-B1-1802 form. You submit it to your insurer.
- Policy review: Your insurer (or a new carrier) applies the applicable credits. In some cases, a previously non-renewable policy becomes insurable again.
Ready to make your South Florida home insurable again?
Request a free roofing estimate
Or call Bigfoot Windows & Roofing at 786-886-2088
Related Articles


Who We’re Not the Right Fit For
- Homeowners who only need an insurance consultation: Bigfoot is a roofing and windows contractor, not an insurance agent or public adjuster. For policy advice, rate shopping, or claims disputes, you need a licensed insurance professional.
- Buyers who need a two-week installation guarantee: Bigfoot cannot guarantee installation within two weeks of contract signing due to county permitting, material delivery, and inspection scheduling requirements — especially in Miami-Dade and Broward where permit review alone can take two to six weeks.
- Homeowners whose primary goal is the cheapest possible bid: Bigfoot pulls permits, handles structural scope in-house, and installs systems that pass Miami-Dade wind-mitigation inspections. If the goal is the lowest number on paper without regard to scope completeness, there are contractors who will provide that — but the wind-mit report and insurance outcome may reflect the difference.
- Properties needing electrical, plumbing, or HVAC scope: Bigfoot’s license authority covers general contracting, roofing, residential contracting, and glass and glazing. Work requiring a separate electrical, plumbing, or mechanical license needs a licensed specialist in those trades.
Common Questions
Frequently Asked Questions
What is force-placed insurance?
Force-placed insurance is coverage a mortgage lender orders on your home when your homeowner’s policy lapses or is cancelled. It protects the lender’s financial interest — not yours. It typically covers only the structure, not personal property or liability, and almost always costs more than a standard policy for the same coverage level. You can cancel it by providing proof of a replacement policy to your lender.
What is a CLUE report and how does it affect my Florida home insurance?
A CLUE (Comprehensive Loss Underwriting Exchange) report is a database record of property insurance claims at an address, maintained by LexisNexis and covering a multi-year lookback period. It follows the property — not just the owner — so a new buyer can be affected by claims filed by the previous owner. Florida insurers query CLUE when underwriting new policies. You are entitled to one free CLUE report per year and can dispute inaccurate entries.
Why do insurers check my credit score for home insurance?
Insurers use a proprietary insurance score — calculated from credit data like payment history, open accounts, and recent inquiries — to predict the statistical likelihood of a future claim. It is a soft pull that does not affect your FICO score. A lower insurance score can result in a higher premium or a declination. Over time, paying down revolving balances and removing collection accounts may improve your insurance score, though results vary by individual credit profile.
Why was my Florida home insurer shut down?
Florida’s insurance market has experienced significant carrier insolvencies since 2021, driven by high hurricane losses, reinsurance cost increases, and litigation costs. Admitted carriers that become insolvent trigger FIGA (Florida Insurance Guaranty Association) coverage up to statutory limits. Surplus lines carriers carry no such backstop. Before binding a policy, ask your agent for the carrier’s Demotech or AM Best rating to gauge financial stability.
How do past water claims at a property affect my home insurance in Florida?
Past water claims — roof leaks, plumbing failures, mold remediation — appear in the CLUE database. Underwriters view repeated water claims as a signal of ongoing maintenance issues or poor construction. Even claims filed by a previous owner can cause a new buyer to receive higher premiums or be declined coverage. Requesting the property’s CLUE report before closing is one of the most useful steps a South Florida buyer can take.
Can a new roof help me get better home insurance rates in Miami-Dade?
A qualifying new roof — properly permitted and inspected — can make your home insurable again after a non-renewal and unlock wind-mitigation credits on your premium. The OIR-B1-1802 wind-mitigation inspection form, completed after your roof passes county inspection, is what you submit to your insurer. Improvements like hurricane strap upgrades and a secondary water barrier underlayment each contribute to the credit categories that affect the final premium calculation.
Can I use PACE financing to pay for a roof replacement in South Florida?
Yes. PACE financing is paid through your property tax bill — it is not a traditional bank loan — and does not require a credit score approval in the conventional sense. PACE rates vary by program and term; ask your contractor or PACE provider for current rate disclosures. A 20-year PACE term produces the lowest monthly payment. PACE programs often require separate applications for different trades — confirm with your PACE provider whether roofing and window scopes can be combined. You may also be able to stack a My Safe Florida Home grant on top of PACE financing — see mysafeflhome.com for current program limits and eligibility requirements.[4]
Schedule Your Free Estimate
Ready to get started? Request a free estimate — no phone call required.
Sources
- Florida OIR-B1-1802 Uniform Mitigation Verification Inspection Form — floir.com
- Bigfoot Windows & Roofing — Why Roofing Quotes Are So Different in South Florida — bigfootwindowsandroofing.com
- Bigfoot Windows & Roofing — Metal Roof Cost Florida Pricing Guide — bigfootwindowsandroofing.com
- My Safe Florida Home Program — mysafeflhome.com
A new qualifying roof is the most concrete step you can take toward keeping your South Florida home insurable.
Bigfoot handles roofing, structural modifications, permits, and inspections under one contractor — no separate GC required.
Questions? Call 786-886-2088